
Best Flood Insurance Options in 2026: NFIP vs. Private Coverage

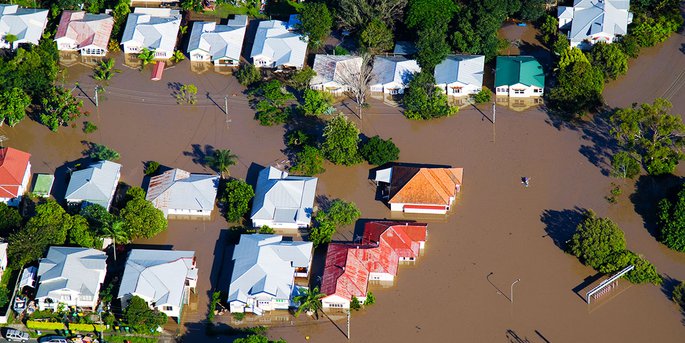
A flood policy can help pay for a ruined furnace. That does not mean it will replace the sofa beside it. Where your belongings sit, how the water entered and which policy you bought can all change the claim.
The best flood insurance starts with a choice between the federally backed National Flood Insurance Program (NFIP) and private coverage. For a typical one-to-four-family home, NFIP limits are $250,000 for the building and $100,000 for belongings, purchased separately. Private policies may offer higher limits and additional benefits, but the details vary.
Below, we compare seven established routes to coverage using FEMA guidance and insurers’ published product information. This is a feature comparison, not a ranking based on a matched quote sample. No company is the cheapest for every address.
For New Yorkers, start with the basement, the building’s flood policy and the cost to rebuild. A familiar insurance logo matters less than the coverage those three questions reveal.
Seven Flood Insurance Options to Compare
- Allstate — An agent-assisted NFIP option
- Chubb — Higher limits for eligible homeowners
- Liberty Mutual — NFIP coverage through an existing insurer
- GEICO — Flood coverage through an insurance agency
- USAA — A starting point for eligible military households
- Assurant — An NFIP policy and servicing option
- Farmers — NFIP coverage with agent support
Compare Home and Flood Insurance Options
The quote offers below include homeowners or renters products. Those policies generally do not include flood coverage: request a separate flood quote and confirm the product before buying. Our provider profiles link to the insurers’ flood information.

Allstate: An Agent-Assisted NFIP Option


Allstate offers NFIP policies through its agents. That can be convenient if you want someone to explain the difference between coverage for your building and coverage for your belongings.
Allstate is one of multiple NFIP sellers; it is not the only place to buy the federal policy. An NFIP quote is not cheaper simply because it carries Allstate’s name. Ask whether the application includes both coverages, what deductible applies to each and whether any property or community discount is reflected.
Watch for: The federal policy’s limitations on basement belongings and temporary housing. A homeowners bundling promotion should not be read as a promised flood discount.
For the separate home policy, see our Allstate homeowners insurance review. The table below summarizes the flood product, using Allstate’s official information and FEMA’s residential limits.
| Feature | Verified detail | What to check |
|---|---|---|
| Policy route | NFIP through Allstate agents | Request flood coverage explicitly |
| Residential building limit | Up to $250,000 | Does your rebuilding estimate exceed it? |
| Residential contents limit | Up to $100,000 | Select this coverage separately |
| Temporary housing | Not included in NFIP | Plan for displacement costs |
Sources: Allstate and FEMA/NFIP coverage guidance. PropertyNest review. As of September 2026. Limits shown are for typical one-to-four-family residential NFIP policies.
Chubb: Higher Limits for Eligible Homeowners

Chubb’s Personal and Excess Flood Insurance is available to Chubb homeowners policyholders. The company advertises up to $15 million in combined coverage for a home and its contents, subject to underwriting and policy terms.
Its published features include replacement-cost protection, added finished-basement protection and temporary-living-expense coverage. These are reasons to obtain a quote when the NFIP limits leave a sizable gap. They are not a promise that every building qualifies or every basement item is covered.
Watch for: Eligibility, the actual limit offered and category-specific limits on valuables. The $15 million figure is a combined property limit, not a separate allowance for cars or each category of belongings. Source: Chubb’s product page.
| Feature | Published benefit | Important condition |
|---|---|---|
| Combined home and contents | Up to $15 million | Subject to underwriting and issued limits |
| Temporary living expenses | Up to $7,500; higher limits available | Additional premium for higher limits |
| Protective measures | Up to $5,000 | Eligible expenses when a flood warning is issued |
| Purchase eligibility | Chubb homeowners policyholders | Confirm property and state availability |
Source: Chubb flood insurance. PropertyNest review. As of September 2026. Published maximum benefits depend on eligibility, underwriting and policy terms.
Liberty Mutual: NFIP Coverage Through an Existing Insurer

- Available in 50 states & Washington, D.C.
- Quote access: Online or by phone
Liberty Mutual’s flood offering describes the NFIP’s building and contents coverage. An existing home or auto customer can ask a representative to review flood protection alongside those policies.
The federal coverage limits do not become broader because you also insure a car with Liberty Mutual. Compare the flood declarations page separately from any home-and-auto savings illustration.
Watch for: Two deductibles if you buy both building and contents protection, and the difference between insuring the structure and replacing belongings after depreciation.
Read our Liberty Mutual home insurance review for the separate homeowners product. The flood facts below come from Liberty Mutual’s official page and FEMA guidance.
| Feature | Verified detail | What to check |
|---|---|---|
| Residential building limit | Up to $250,000 | Select an appropriate building amount |
| Residential contents limit | Up to $100,000 | Contents coverage is separate |
| Deductibles | Separate building and contents deductibles | Budget for both if both are damaged |
| Home-and-auto savings | A separate product promotion | Not a guaranteed flood-policy discount |
Sources: Liberty Mutual and FEMA/NFIP coverage guidance. PropertyNest review. As of September 2026. Confirm building and contents selections separately.
GEICO: Flood Coverage Through an Insurance Agency


GEICO Insurance Agency helps customers obtain flood insurance through partner insurers. Its service page directs policyholders to the carrier shown on their paperwork for claims.
That distinction matters: the company that sells the policy and the company that handles a loss may be different. An NFIP policy carries federal backing; GEICO itself is not a government-backed insurance company.
Watch for: The named insurer, whether the quote is for NFIP or private coverage, the effective date and who will service a claim. We found no matched quote evidence that makes GEICO the lowest-priced option for every household.
USAA: A Starting Point for Eligible Military Households
USAA describes both NFIP coverage and private flood options available through its insurance agency. Eligible military households can ask which route fits their building, belongings and lender’s requirements.
There is also a useful exception to the usual renters-insurance rule: USAA says its renters policy includes flood protection. Existing renters customers should check their own contract, limits and exclusions before paying for potentially overlapping coverage. This does not mean a USAA homeowners policy automatically includes flood insurance.
Watch for: Membership and product eligibility, the insurer behind a private quote and whether temporary housing or basement belongings are covered. Source: USAA’s published flood information.
| Product | USAA describes | What to check |
|---|---|---|
| NFIP flood policy | Federal program coverage | Building and contents limits and deductibles |
| Private flood policy | Options through USAA Insurance Agency | Named insurer, terms and lender acceptance |
| USAA renters policy | Flood protection included | Existing limits and exclusions before adding coverage |
| USAA homeowners policy | Separate flood coverage may be needed | Do not apply the renters exception to a house |
Source: USAA flood information. PropertyNest review. As of September 2026. Membership, product eligibility and policy conditions apply.
Assurant: An NFIP Policy and Servicing Option

Assurant participates in the NFIP’s Write Your Own program and describes in-house policy servicing and claims support. Its listed NFIP property types include single-family homes, two-to-four-family buildings and residential condominium units.
Ask the agent which legal insurance company will issue your policy and which contract you are being quoted. A company’s commercial flood extras do not automatically apply to its residential NFIP policy.
Watch for: The same federal limits and exclusions that apply to comparable NFIP policies elsewhere. We do not have comparable household quotes supporting a claim that Assurant consistently has lower flood premiums. Source: Assurant’s official NFIP information.
| Feature | Official product information | What to check |
|---|---|---|
| NFIP role | Write Your Own provider | Legal insurer named on your documents |
| Residential property types | Single-family and two-to-four-family homes | Property and community eligibility |
| Condominium coverage | Individual units and association policies listed | Choose the correct policy for the insured interest |
| Pricing comparison | NFIP rules apply to equivalent federal coverage | No matched quotes establish a lowest-price ranking |
Sources: Assurant NFIP information and FEMA coverage guidance. PropertyNest review. As of September 2026. Confirm the issuing insurer and policy form.
Farmers: NFIP Coverage With Agent Support
Farmers says it offers NFIP-backed flood insurance in all 50 states. Availability still depends on NFIP community and property eligibility; a nationwide offering is not a guarantee that every address qualifies.
Ask a Farmers agent for an address-specific quote with separate building and contents limits. The older split between “Standard Risk” and “Preferred Risk” policies is not the current way to shop: FEMA’s Risk Rating 2.0 replaced the Preferred Risk Policy product.
Watch for: A home or auto discount being mistaken for a reduction in the federal flood rate. The table summarizes the official Farmers flood offering and FEMA limits.
Related homeowners quote option: Farmers. Request flood coverage separately.
| Feature | Verified detail | What to check |
|---|---|---|
| Purchase route | NFIP through Farmers agents | Request a separate flood quote |
| Geographic offering | All 50 states, according to Farmers | NFIP community and property eligibility still apply |
| Typical residential limits | $250,000 building; $100,000 contents | Coverage amounts are selected separately |
| Preferred Risk Policy | Replaced under Risk Rating 2.0 | Obtain a current address-specific quote |
Sources: Farmers flood insurance and FEMA/NFIP coverage guidance. PropertyNest review. As of September 2026. Community and property eligibility apply.
How PropertyNest Compared These Flood Insurance Options
PropertyNest reviewed FEMA/NFIP coverage and pricing guidance, official insurer product descriptions and New York government resources. We retained the seven providers covered by this guide and compared the product offered, purchase route, limits and important conditions. This is not a census of every insurer or a claims-service test.
We have not collected a matched set of address-level flood quotes for these companies. Accordingly, we do not publish a PropertyNest average premium, price ranking or numerical quality score. Homeowners ratings and complaint figures cannot stand in for a dated, flood-specific comparison.
Tables are labeled PropertyNest Data and identify the underlying sources. Published maximum benefits are not guaranteed offers. The insurer’s issued policy controls. Compensation from a quote link does not make a product the best fit for a particular home.
What Does Flood Insurance Cover?
Flood insurance pays for covered physical damage caused by flooding, within the policy’s limits. NFIP coverage can be purchased for a building, its contents or both. A renter usually needs contents coverage; a homeowner may need both.
The NFIP definition generally requires temporary inundation of at least two acres of normally dry land or at least two properties, including yours. Covered causes include overflowing inland or tidal water, rapid surface-water accumulation or runoff, and qualifying mudflow. A landslide is not the same as mudflow.
A burst pipe inside one apartment is a different insurance question. A flood policy does not turn every kind of water damage into a covered claim.
Building coverage and contents coverage are different
FEMA’s buying guide places structural and installed systems—such as the foundation, electrical and plumbing systems, furnace, water heater and built-in cabinetry—under building coverage. Movable belongings, such as clothing, furniture, electronics and a washer or dryer, generally fall under contents coverage. Location and policy restrictions still apply.
Do not assume the building limit is also a belongings limit. NFIP building and contents coverage are selected separately and have separate deductibles. Private insurers can use different terms, so compare the actual forms.
Who Needs Flood Insurance?
Flood insurance is generally required for a building in a Special Flood Hazard Area when it secures a federally regulated or backed loan and NFIP coverage is available. A lender may also require coverage outside those areas. Certain previous disaster-assistance awards carry continuing insurance obligations.
A paid-off mortgage removes a lender from the conversation; it does not remove flood risk. Consider what you could afford to replace if uninsured water damage reached your first floor or building systems.
A mortgage requirement does not always mean you must choose NFIP. Federal banking rules require acceptance of qualifying private flood policies; other policies may be accepted under additional criteria. Give your lender the proposed policy before switching and confirm that it meets the loan’s coverage requirements.
New York: Look beyond the coastal flood zone
Check your address using New York City’s flood-map resources, then consider rainfall flooding as well as coastal surge. The city’s extreme-rainfall guidance and stormwater maps address a different part of the risk picture. A map showing lower coastal risk is not a promise of a dry basement.
Ask where the lowest occupied floor, boiler, electrical equipment and stored belongings sit. For a condo or co-op, request the building’s flood declarations and ask your own agent to identify gaps affecting your unit and possessions. A building policy should not be assumed to replace every resident’s belongings.
The city identifies more frequent and intense rainfall as a climate risk. The practical response is specific: review drainage, entry points, vulnerable equipment and coverage when renewing.
Basement Coverage: Read This Before Buying
A finished basement may feel like another floor of your home. An NFIP policy treats it differently. A basement is generally an area with a floor below ground level on all sides, and substantial coverage restrictions apply.
FEMA’s basement guidance lists certain covered building equipment, including furnaces, water heaters and central air-conditioning equipment. Eligible contents can include a washer, dryer, freezer and window air conditioner when the appropriate coverage is purchased and conditions are met.
It generally does not cover the basement sofa, television or finished floors and walls. An NFIP contents policy is therefore not blanket protection for a furnished basement apartment. Ask the agent to identify covered items in writing; compare a private policy if its basement coverage addresses your needs.
Other gaps to check
NFIP does not provide additional living expenses such as a hotel while your home is repaired. Cars, outdoor landscaping and many exterior features are also outside its coverage. Preventable mold damage can be excluded. Private policies may cover some of these gaps, but “private” alone tells you little about a particular contract.
NFIP Versus Private Flood Insurance
The NFIP is a federal program administered by FEMA and offered through participating insurers, agents and NFIP Direct. It is available in participating communities, subject to property eligibility. A private flood policy is backed by an insurance company rather than the federal program.
For typical one-to-four-family residential NFIP policies, building coverage tops out at $250,000 and contents coverage at $100,000. Other building types, including condominium-association buildings and commercial properties, have different rules. Do not apply a single-home limit to an entire apartment building.
How claims are valued
NFIP belongings claims use actual cash value, which accounts for depreciation. Certain single-family principal residences qualify for replacement-cost settlement on the building if insured for at least 80% of replacement cost or the maximum available NFIP amount. FEMA explains those conditions in its NFIP questions-and-answers guide. A replacement-cost settlement still cannot exceed applicable policy limits.
Private policies may offer replacement cost on belongings and higher building limits. Ask about both; a high headline limit does not answer how a worn-out appliance will be valued.
When an excess policy makes sense
A primary private policy can replace the NFIP policy if it meets your needs and any lender requirements. An excess policy adds a layer above a specified underlying flood policy. Some insurers offer a flood endorsement to an existing home policy. These are different arrangements: confirm which one you are buying, when it begins paying and what exclusions carry through.
PropertyNest calculation—illustration, not market data: A home with a hypothetical $600,000 rebuilding cost and $250,000 of NFIP building insurance has a $350,000 difference between those two amounts. The NFIP limit equals 41.7% of that rebuilding estimate ($250,000 ÷ $600,000). This is a coverage-planning illustration, not a forecast of a claim payment, premium or average New York home value.
How Much Does Flood Insurance Cost?
Your address matters more than an undated national average. FEMA’s current pricing explanation identifies location, foundation, first-floor height, building use, rebuilding cost, coverage limits and deductibles among the inputs. Flood zone alone does not determine the price.
For the same property information and coverage selections, NFIP providers use the federal pricing approach. Differences between quotes may reflect different inputs or selected coverage, rather than one brand offering a better federal rate. Private flood quotes can vary by insurer and are worth comparing on equivalent terms.
Compare the total annual payment, including fees and surcharges, rather than an isolated premium component. Ask whether the current charge includes a discount that may change at renewal. Community mitigation discounts are distinct from a home-and-auto bundling offer.
The old Preferred Risk Policy is no longer offered under Risk Rating 2.0; FEMA’s transition FAQ explains the change. Older advertisements quoting a low flat annual price should not be treated as current offers for your home.
We are not presenting a 2026 New York sample average here because we have not verified a comparable current quote sample. Request a quote for your address through an agent or the NFIP’s official quote tool.
Check deductibles before choosing the cheaper premium
NFIP building and contents deductibles apply separately. In a simplified hypothetical loss with $20,000 in covered building damage and $10,000 in covered contents damage, a $2,000 deductible on each would leave $4,000 in combined deductibles. Payments would total $26,000 if the losses were valued as stated, fully eligible and within all limits. Depreciation and exclusions could reduce payment further.
Waiting periods and closing dates
New NFIP coverage generally has a 30-day waiting period. Exceptions can apply, including coverage obtained in connection with making, increasing, extending or renewing a loan. Other exceptions have specific conditions; confirm the effective date on your policy.
A private policy’s waiting period depends on the contract and circumstances. There is no universal 10-to-14-day rule. Do not cancel existing coverage or assume protection for an approaching storm before the replacement policy is effective.
The table below compares NFIP and private coverage. Private-policy benefits depend on the product and state; sources appear beneath the table.
| Feature | NFIP: typical one-to-four-family home | Private flood policy |
|---|---|---|
| Building limit | Up to $250,000 | Varies; confirm the amount offered |
| Contents limit | Up to $100,000, purchased separately | Varies; ask about valuables sublimits |
| Contents settlement | Actual cash value, after depreciation | May offer replacement cost; check contract |
| Temporary housing | Not covered | May be available, with limits |
| Basement belongings | Only specified items qualify | Coverage varies; ask about finishes and furniture |
| Waiting period | Generally 30 days; exceptions apply | Product-specific; no universal 10–14-day rule |
| Pricing | Federal method for equivalent inputs and coverage | Varies by insurer and property |
| Eligibility | Participating community and eligible property | Insurer underwriting and state availability |
| Lender requirement | Confirm sufficient limit and continuous coverage | Obtain lender acceptance before switching |
Sources: FEMA/NFIP coverage guidance, NFIP purchase guidance and the official insurer sources linked above. PropertyNest comparison. As of September 2026. Private-policy terms vary; this is not a premium survey.
Flood, Wind and Sewer Backup Are Different Claims
A storm can produce several kinds of damage, with different policies responding. Wind that tears off a roof is a homeowners or windstorm coverage question. Rising floodwater is a flood-insurance question. A sewer backup may require separate water-backup coverage, depending on its cause and policy wording.
New York’s Department of Financial Services explains these coverage differences. Home policies often cover some sudden and accidental interior water damage, but maintenance exclusions and specific limits still matter. Water touching the ground is not, by itself, a complete legal test of flood coverage.
Check the trigger for any hurricane or wind deductible. If a hypothetical policy uses a 5% deductible on $500,000 of dwelling coverage, that deductible is $25,000—not 5% of the repair bill. A covered $30,000 loss would leave a potential $5,000 payment in that simplified example, subject to all other terms. The percentage and trigger vary; do not assume every New York policy uses 5%.
How to Compare Flood Quotes Without Missing a Gap
- Describe the property consistently. Use the same address, occupancy, foundation, floor height and rebuilding estimate for each quote. Correct an inaccurate application before comparing prices.
- Match limits and deductibles. Write down the building limit, contents limit and each deductible. A cheaper quote with less coverage answers a different question.
- Check loss settlement. Ask which property is paid at replacement cost and which is depreciated. Review valuables sublimits separately.
- Read the basement and housing provisions. Ask about furniture, finishes and temporary accommodation specifically. These can matter more than a small annual saving.
- Confirm the insurer and lender acceptance. An agency name is not always the company paying claims. Send the proposed policy to your lender and check the effective date before switching.
- Keep the documents. Save the quote, application, declarations, endorsements and inventory photos. Put a renewal reminder on your calendar and revisit coverage after renovations or a change in how you use the property.
Renters, condo owners and co-op shareholders
Ask your landlord or building manager what the building insures, then protect your own belongings as needed. A landlord’s flood policy does not automatically cover a tenant’s furniture. A condo or co-op building policy also needs to be considered alongside the resident’s own coverage.
For a broader review of the building-versus-unit distinction, see PropertyNest’s NYC homeowners, condo and co-op insurance guide. Renters can also review what renters insurance covers before adding another policy.
After a Flood: Claims and Disaster Assistance
Report the loss promptly to the appropriate insurer. When it is safe, photograph damage and make an inventory with approximate ages and replacement costs. Keep receipts and ask the adjuster about documentation and proof-of-loss deadlines. Follow emergency instructions before entering a damaged building.
The NFIP claims checklist provides a practical starting point. If a loss involves both wind and flooding, notify the relevant insurers rather than assuming one will handle everything.
Disaster assistance is not a substitute for an insurance policy. FEMA explains that its assistance to eligible survivors includes grants that generally do not have to be repaid; SBA disaster loans are a different form of help. Assistance depends on the declaration, program and eligibility, and cannot duplicate insurance benefits. It is not universally limited to a $5,000 loan.
Frequently Asked Questions
- Selection Criteria: Companies are chosen based on customer service, affordability, and coverage diversity.
- Data Collection: Data is amassed from credible sources, customer surveys, and industry reports.
- Analysis: A robust analysis, employing a scoring system, is conducted to rank the companies.
- Updating: This page is regularly updated to offer the most current information.
- Editorial Integrity: We uphold a transparent editorial process and disclose any affiliations.
- User Engagement: User feedback is integral and factored into our evaluations.
- Accessibility and Usability: Our page is crafted for ease of use, mobile optimization, and wide accessibility.
- Editorial Independence: Our editors and writers work independently, free from influence by advertisers.
- Source Disclosure: All data sources are disclosed and credited.
- Conflict of Interest: Any potential conflict of interest is disclosed to maintain integrity.
- Reviewer Qualifications: The qualifications of reviewers and contributors are provided.
- Update Frequency: The frequency of updates and revisions is clearly stated.
- Correction Policy: A clear policy for correcting errors is in place to uphold accuracy and trust.

